ATTENTION: PROPERTY OWNERS over 60
HOW TO ACCESS YOUR HOME EQUITY WITHOUT SELLING
CLEAR, TAILORED REVERSE MORTGAGE GUIDANCE FROM A TEAM YOU CAN TRUST
CLICK BELOW TO WATCH FIRST!

Next Step: Answer a few questions about your situation.
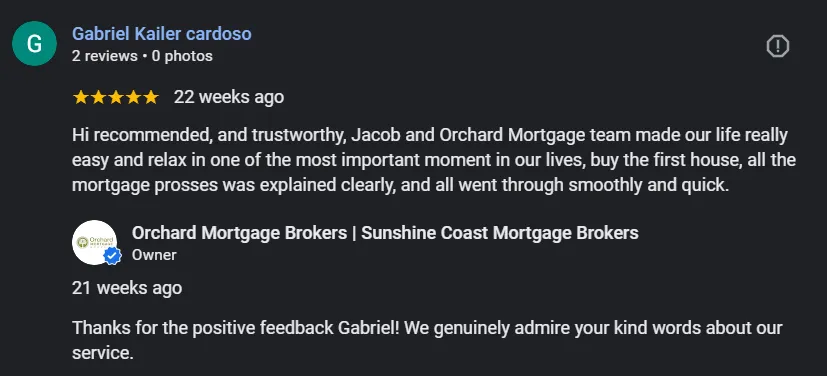
TESTIMONIALS
What others are saying
For Home Owners Over 60 Who Want More Financial Flexibility Without Selling Their Home
Pay off an existing mortgage
Increase Retirement Cash Flow
Renovate or Improve the Home
Cover Medical or Living Expenses
Help Children or Family
Create a Financial Safety Buffer
STILL NOT SURE?
Frequently Asked Questions
Here's what we usually get asked
What is a reverse mortgage and how does it work?
A reverse mortgage allows eligible homeowners, typically aged 60 and over, to access some of the equity in their home without having to sell it. Unlike a traditional home loan, regular repayments are generally not required. Instead, the interest is added to the loan balance over time, which is usually repaid when the home is sold or the borrower permanently leaves the property.
Who is eligible for a reverse mortgage?
Eligibility depends on several factors, including your age, the value of your property and the lender's criteria. In most cases, borrowers must be at least 60 years old and own their home. We can quickly assess your eligibility during a free consultation.
Do I need to make regular repayments?
No. Most reverse mortgages do not require mandatory repayments while you continue living in your home. However, many lenders allow voluntary repayments if you wish to reduce the loan balance over time.
Can I continue living in my home?
Yes. One of the key benefits of a reverse mortgage is that you generally remain the owner of your home and can continue living there, provided you meet the terms of the loan, such as maintaining the property and keeping it insured.
How much of my home equity may I be able to access?
The amount you may be able to borrow depends on factors such as your age, your property's value and the lender's lending criteria. Generally, the older you are, the more equity you may be able to access.
What happens to the loan balance over time?
Because repayments are generally not required, interest is added to the outstanding loan balance. This means the amount owing typically increases over time. However, many properties also increase in value over the long term, so it's important to consider both sides when deciding whether a reverse mortgage is suitable.
Do you service Australia wide?
Yes. We can meet over Zoom or via a phone call and complete your application all remotely.
Do you offer ongoing support?
We review all of our clients' home loans at least once a year. If we believe a better rate is available, we’ll contact the bank on your behalf to negotiate. Additionally, we’ll ensure that your current loan product still meets your needs.
How We Help You Determine Whether a Reverse Mortgage Is Right for You
Learn About Your Options
We start by understanding your goals and explaining how a reverse mortgage works in plain English. We'll discuss the benefits, trade-offs and alternative options so you can make an informed decision.
Receive Personalised Advice
If a reverse mortgage appears suitable, we'll calculate how much equity you may be able to access, explain how the loan could change over time, and recommend the solution that best fits your circumstances.
Ongoing Support
If you decide to proceed, we'll manage the application from start to finish and remain available whenever your circumstances change or you have questions in the future.
Ready to get started?
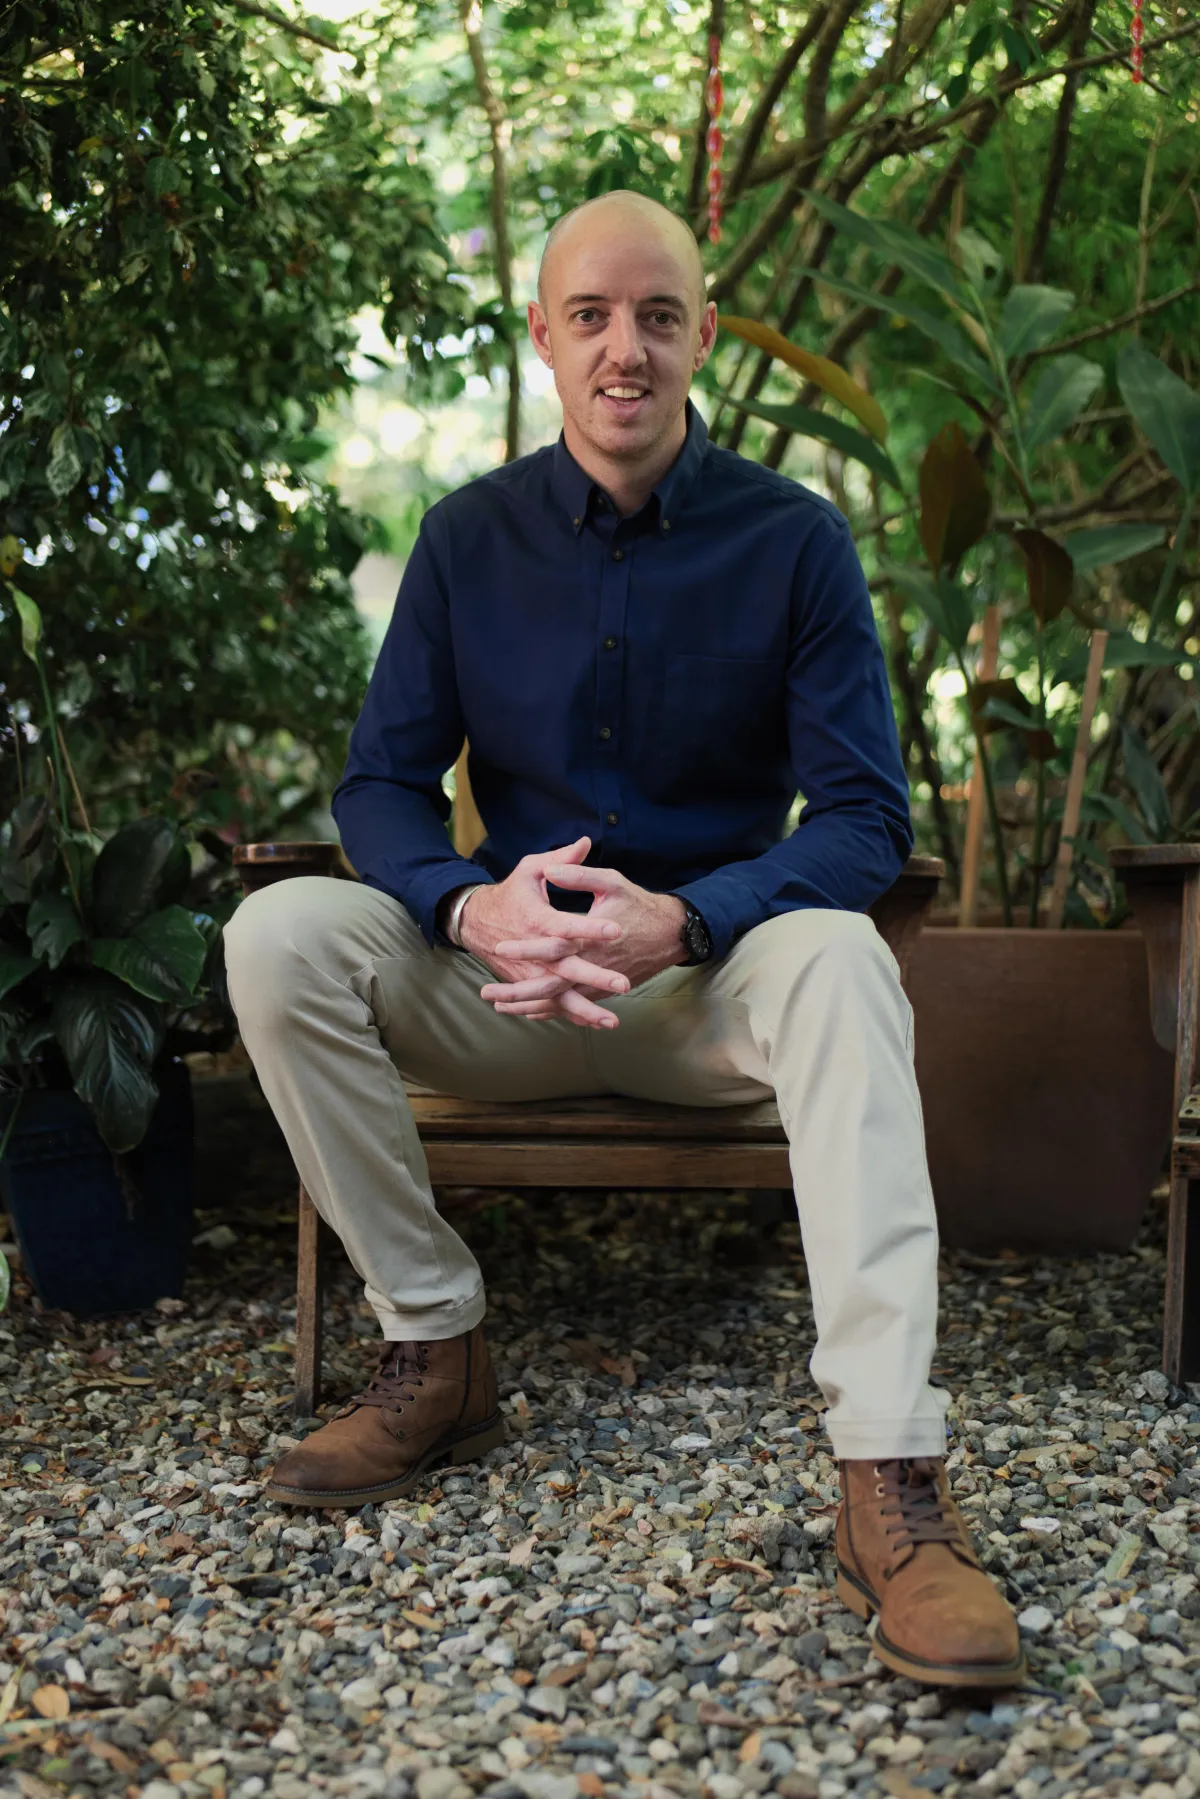
MEET your broker
Hey, I'm Jacob
Our team of Mortgage Brokers brings over 40 years of experience in loan structuring and supporting investment property purchases.
Over $300m of loans settled for our customers
This page provides general information only and has been prepared without taking into account your objectives, financial situation or needs. We recommend that you consider whether it is appropriate for your circumstances and your full financial situation will need to be reviewed prior to acceptance of any offer or product. It does not constitute legal, tax or financial advice and you should always seek professional advice in relation to your individual circumstances. [OPTIONAL based on content]. Subject to lenders terms and conditions, fees and charges and eligibility criteria apply.
Orchard Mortgage Brokers (Qld) Pty Ltd ACN 671 112 137 Trading As Orchard Mortgage Brokers is an authorised Credit Representative 556459 under Australian Credit Licence 389328
Jacob Ferguson is an Authorised Credit Representative 471688 under Australian Credit Licence 389328